The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Income protection insurance and life insurance can both form part of a financial safety net, but they are treated differently for tax purposes. This guide explains the key Australian tax differences between income protection premiums, benefit payments and life insurance payouts so you can better understand how each cover type works.
Income protection insurance and life insurance are often discussed together because both are designed to help manage financial risk. However, they do different jobs and their tax treatment is not the same.
Income protection is generally focused on replacing part of your income if illness or injury prevents you from working. Life insurance is generally focused on providing a lump sum to nominated beneficiaries if the insured person dies or, in some cases, is diagnosed with a terminal illness.
This article explains the main tax differences between the two types of cover in an Australian context. It is general information only and does not take your personal objectives, financial situation or tax position into account.
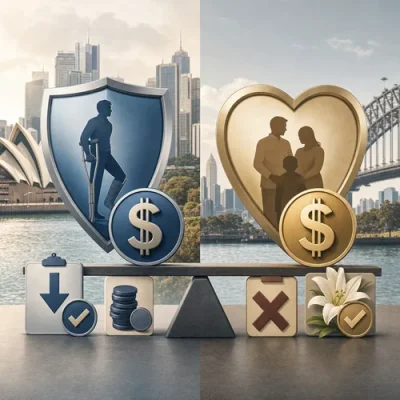
Income protection and life insurance at a glance
The biggest tax distinction comes from the purpose of each product. Income protection is connected to your ability to earn income, while life insurance is usually designed to provide a capital-style lump sum for your family or other beneficiaries.
| Feature |
Income protection insurance |
Life insurance |
| Main purpose |
Helps replace part of your income if you cannot work due to illness or injury. |
Provides financial support to beneficiaries if the insured person dies or is diagnosed with a terminal illness, depending on the policy. |
| Typical benefit structure |
Usually paid as ongoing monthly benefits after a waiting period, subject to the policy terms. |
Usually paid as a lump sum. |
| Premium tax treatment |
Premiums for a personally held policy are generally tax-deductible where the cover relates to income replacement. |
Premiums are generally not tax-deductible because they are usually treated as a private expense. |
| Benefit tax treatment |
Claim payments are generally treated as assessable income. |
Death benefit lump sums are generally received tax-free by beneficiaries, although ownership and superannuation structures can affect the outcome. |
What income protection insurance is designed to do
Income protection insurance is designed to provide a financial safety net if you are unable to work because of illness or injury. Rather than paying one large lump sum, it generally provides monthly payments based on a portion of your pre-disability income.
Payments usually begin after a waiting period and can continue until you return to work or until the maximum benefit period under the policy is reached. If you want more background on benefit triggers, exclusions and payment timing, see this guide to what income protection insurance covers.
Income protection can be particularly relevant for people whose household expenses would be difficult to meet if their income stopped for a period. This may include employees, self-employed workers, business owners and people with ongoing financial commitments.
What life insurance is designed to do
Life insurance is a contract between an individual and an insurer that is designed to provide financial protection for beneficiaries if the insured person dies. Depending on the policy, a benefit may also be payable if the insured person is diagnosed with a terminal illness.
The benefit is usually paid as a lump sum. Beneficiaries may use the money for purposes such as mortgage repayments, education costs, everyday bills or other financial obligations, depending on their circumstances.
Life insurance is often considered by people who have dependants, debts or other financial responsibilities that could continue after their death. A life insurance calculator can help illustrate the kinds of expenses that may be considered when thinking about cover levels, although it does not replace personal advice.
Tax treatment of income protection premiums
For many Australian taxpayers, premiums paid for a personally held income protection policy are generally tax-deductible. This is because the policy is intended to protect assessable income by replacing lost earnings if illness or injury prevents you from working.
To support a deduction, it is important to keep accurate records of the premiums paid during the financial year and to ensure the claim is reported correctly in your tax return. Individual circumstances can affect deductibility, so the Australian Taxation Office rules and professional tax guidance should be considered where needed.
The ownership structure matters. Policies held and paid through superannuation can have different tax implications from policies held personally. For more on this distinction, see income protection inside superannuation versus outside superannuation.
Tax treatment of income protection claim payments
While premiums for eligible income protection cover are generally deductible, benefit payments are usually treated as assessable income. In practical terms, this means claim payments can be taxed in a similar way to employment income, because the benefit is intended to replace wages or business income.
This is a key difference from many life insurance death benefit payments. Income protection benefits are usually regular income-style payments rather than capital lump sums for beneficiaries.
When reviewing income protection, it can be useful to consider the relationship between your income, the waiting period, the benefit period and the amount of cover available under the policy. An income protection insurance calculator may help you explore broad cover-level scenarios, subject to policy and eligibility rules.
Tax treatment of life insurance premiums
Life insurance premiums in Australia are generally not tax-deductible when the policy is held for personal protection purposes. The reason is that life insurance is usually considered a private expense: it is intended to provide financial support to beneficiaries, rather than replace your own assessable income while you are alive and unable to work.
There may be different tax outcomes depending on how the policy is owned. For example, life insurance held inside superannuation may involve premiums being paid from superannuation contributions, which can create different tax and cash-flow effects from paying premiums personally. The correct treatment depends on the structure and your circumstances.
Tax treatment of life insurance payouts
Life insurance death benefit payments are generally received tax-free by beneficiaries when paid from a personally owned policy. This reflects the fact that the payment is typically a lump sum for beneficiaries rather than a replacement of the insured person's taxable income.
However, tax treatment can become more complex if the policy is owned by an entity, such as a company, or if the policy is held through superannuation. The source article also notes that ownership and estate arrangements can influence whether beneficiaries receive the intended benefit without unexpected complications.
Australia does not have inheritance tax, but life insurance proceeds may still interact with estate planning. If a benefit forms part of the policyholder's estate, issues such as estate debts or disputes may affect the timing and distribution of proceeds. Legal and financial advice can help clarify how a policy should be structured.
Choosing between income protection and life insurance
Income protection and life insurance are not direct substitutes. They respond to different risks, at different times, and with different tax consequences.
Consider the risk you are trying to manage
If the main concern is how you would meet living costs while recovering from an illness or injury, income protection may be the more relevant type of cover to understand. It is designed around income continuity during your working life.
If the main concern is how dependants would manage financially after your death, life insurance may be more relevant. It is designed around longer-term support for beneficiaries and can be an important part of estate planning.
Consider dependants and financial commitments
People with dependants, a mortgage, education costs or other household obligations may consider how both short-term income disruption and death would affect the family's financial position. The answer may not be one product or the other; some people use both types of cover for different purposes.
Consider ownership structure
Whether cover is held personally, through superannuation or through another entity can affect both tax and claim outcomes. This is especially important because the tax treatment of premiums and benefits may differ depending on the arrangement.
When both types of cover may work together
In some financial plans, income protection and life insurance are layered together because they protect against different events. Income protection focuses on income during illness or injury. Life insurance focuses on a lump sum for beneficiaries if the insured person dies.
This layered approach may be relevant for people with complex financial commitments, business responsibilities or dependants who rely on their income. It can also reflect different life stages: protecting current income while also planning for long-term family security.
The right structure depends on personal circumstances, policy terms, affordability and tax position. A licensed professional, such as a broker or adviser, can explain how different policy structures work and how tax considerations may apply.
Key takeaways
- Income protection premiums for personally held cover are generally tax-deductible when the policy protects assessable income.
- Income protection claim payments are generally taxable as assessable income.
- Life insurance premiums are generally not tax-deductible when held for personal protection purposes.
- Life insurance death benefit payouts from personally held policies are generally received tax-free by beneficiaries.
- Superannuation, company ownership and estate arrangements can change the tax and distribution outcome.
- Income protection and life insurance can complement each other because they address different financial risks.
Final thoughts
The tax differences between income protection and life insurance are important because they reflect the different purpose of each product. Income protection is generally connected to earning capacity, which is why eligible premiums may be deductible and claim payments are usually taxable. Life insurance is generally designed to provide a lump sum for beneficiaries, which is why premiums are usually not deductible and death benefit payouts are often tax-free.
Because tax outcomes can depend on ownership, superannuation arrangements and personal circumstances, it is sensible to seek qualified tax, legal or financial advice before relying on a particular structure.
Published: Wednesday, 9th Apr 2025
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.